
 Trade W
Why P/E Ratio is Crucial for Stock & Index Traders
If you've ever questioned if a stock was worth its price tag, you're already weighing out the options like a trader. The Price-to-Earnings ratio (P/E ratio) is one of the most basic ways to look at this question. Think of it this way: when you go into a store to buy a laptop, you look at the price compared to what you’re getting, right? Storage capacity, processing speed, battery life. The P/E ratio does the same thing with a stock. It shows you how much you are paying for every dollar of the company’s earnings.
Here’s the short and simple: stock price is what you are paying, and earnings is what the company is actually ripping in. The P/E ratio is your price to value meter. In other words, when Apple trades at a P/E of 28, it means the market is willing to pay $28 for every dollar of Apple’s annual earnings. That may sound expensive, but the market is pricing that stock, or earning, based on some confidence of future growth in the company.
Let's simplify this further. Imagine you are thinking about buying a stake in a gaming company. The stock price is $100 and the company is earning $5 a share. Therefore its P/E is 20. Are you paying $20 for ever dollar of earning? Is that a good deal? Well, that depends on the sector, growth opportunities and how other stocks trade.
For example, depending on what you are trading, the P/E is still significant whether you are trading indices or CFDs as opposed to stocks. Index valuations are simply a weighted average of the P/Es of its component stocks. A current S&P 500 P/E that is higher than its historical average, implies that the entire market may be expensive. This is useful for CFD traders to determine risk, since overvalued markets can be riskier, ie. more volatile.
A business that trades at high P/E level will have a exponentially more difficult time maintaining that level than its cost-to-replace value. An investor will seldom withhold too much of his/her peak income opportunity, keepingin mind other investment opportunities and their respective payback periods, unless the opportunity has some significant other characteristic (a la shenanigans or rainbow farting unicorns).
The opportunity cost of any capital invested in actually resolving issues also needs to be subjugated to scrutiny.
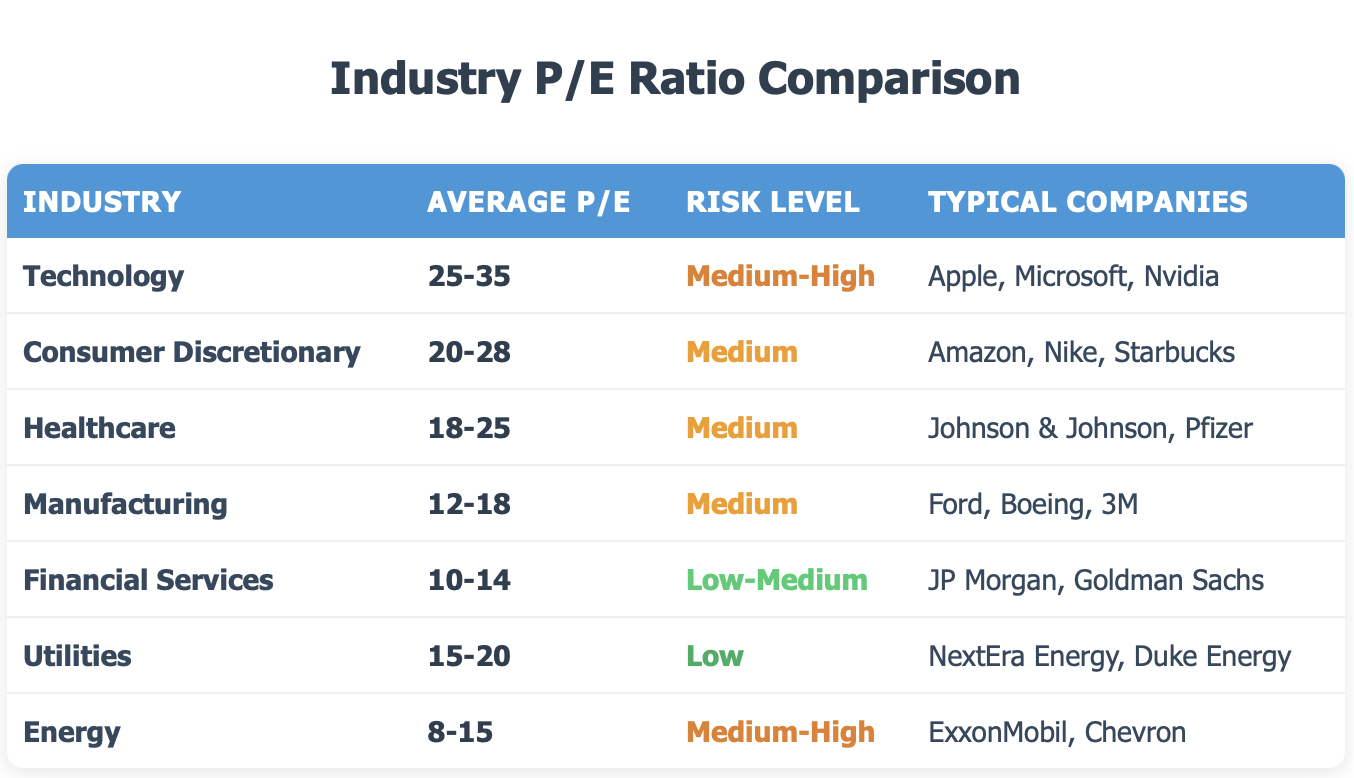
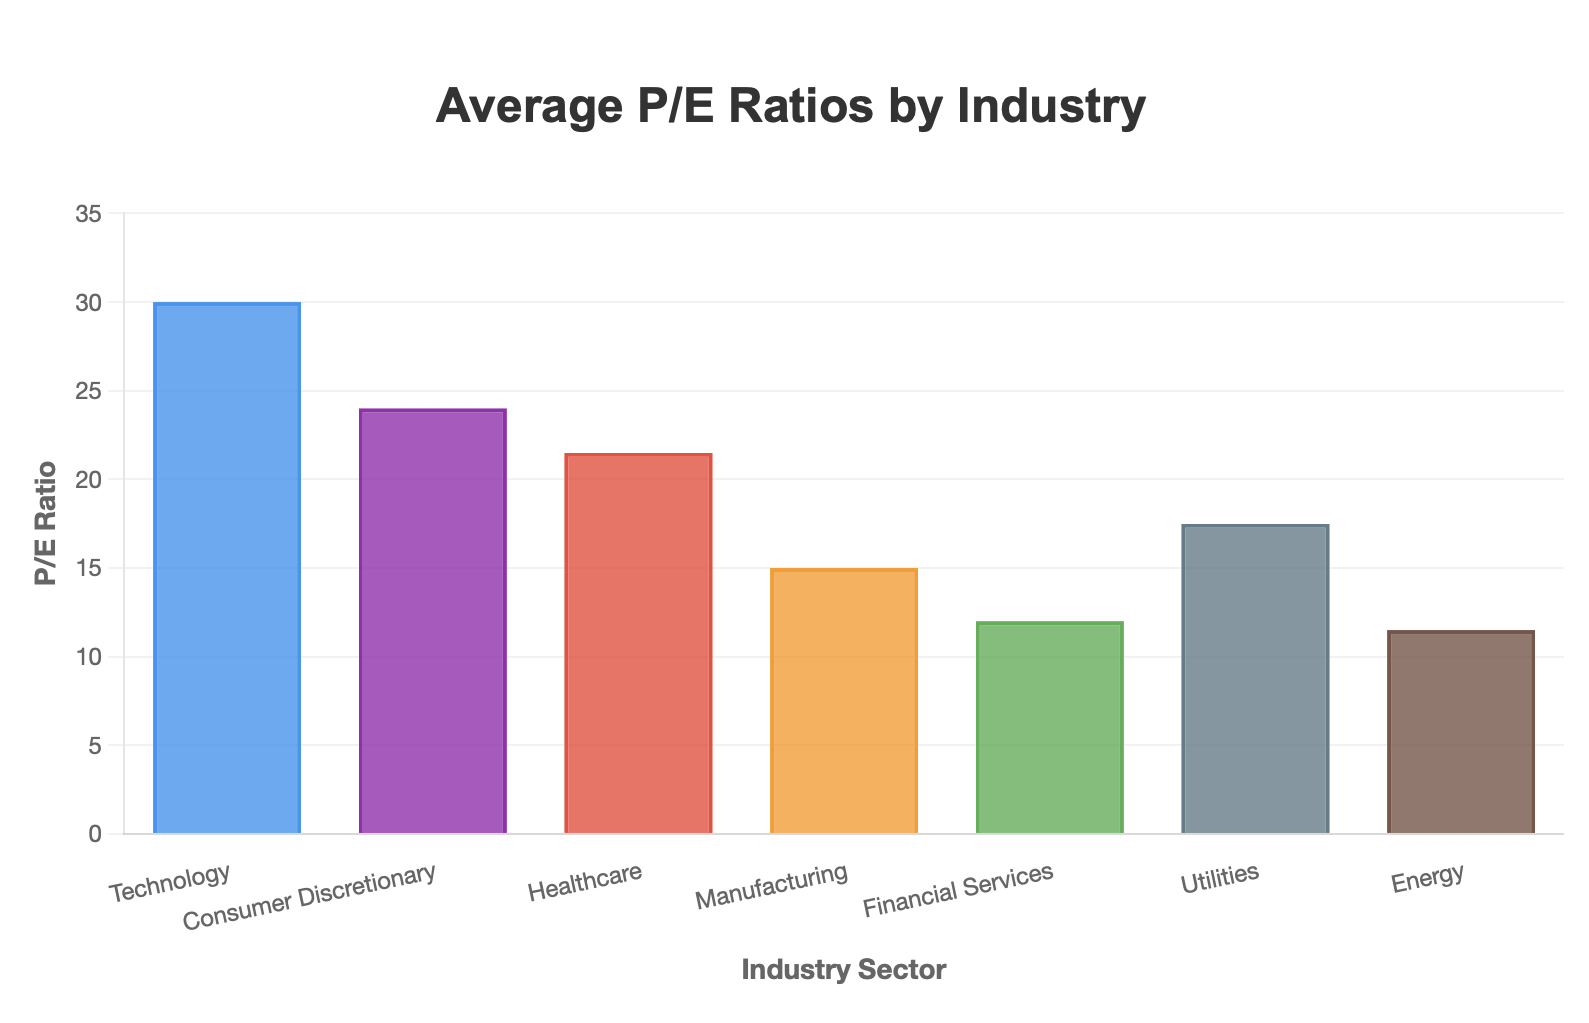
Various sectors trade at completely different P/E levels. Tech companies will frequently have P/E in the 20s or 30s or more for example. This is because investors will project significant growth and customers and/or user bases, will continue well into the future, as a reasonable assumption that the same customer will also return to the same product, combined. A bank or utility may be trading at around 10-15. Neither is more valuable than the other.
Context matters.
Bottom line, a P/E ratio is not just a meaningless number on a financial statement, it is your guide to valuing stocks, identifying opportunities, and avoiding paying too much.
Core Definition: Understanding P/E Ratio (Price-to-Earnings)
Let's go over how it works. The P/E formula is very simple:
P/E Ratio = Stock Price ÷ Earnings Per Share (EPS)
The stock price is easy to understand, which is the price in the market today per one share. Earnings per share (or EPS) is simply the company's total profit that was stated above (which in this case is $1 million) divided by the total number of shares outstanding. So if a company has a earnings of $1 billion that year and has 100 million shares, then EPS would be $ 1 (which is $1 billion divided by 100 million shares is $10).
Example 1: A stock is $150, and the company reports earnings $5 per share, therefore your P/E would be 30 ($150 ÷ $5) meaning that investors are paying $30 for every dollar of annual earnings.
Example 2: The stock you are interested in is comic book company. The price of the stock is $50, and they said they made $2 per share last year therefore P/E would equal 25 ($50 ÷ $2), essentially you would be paying $25 for each dollar of profit the company made last year.
So what does all it mean?
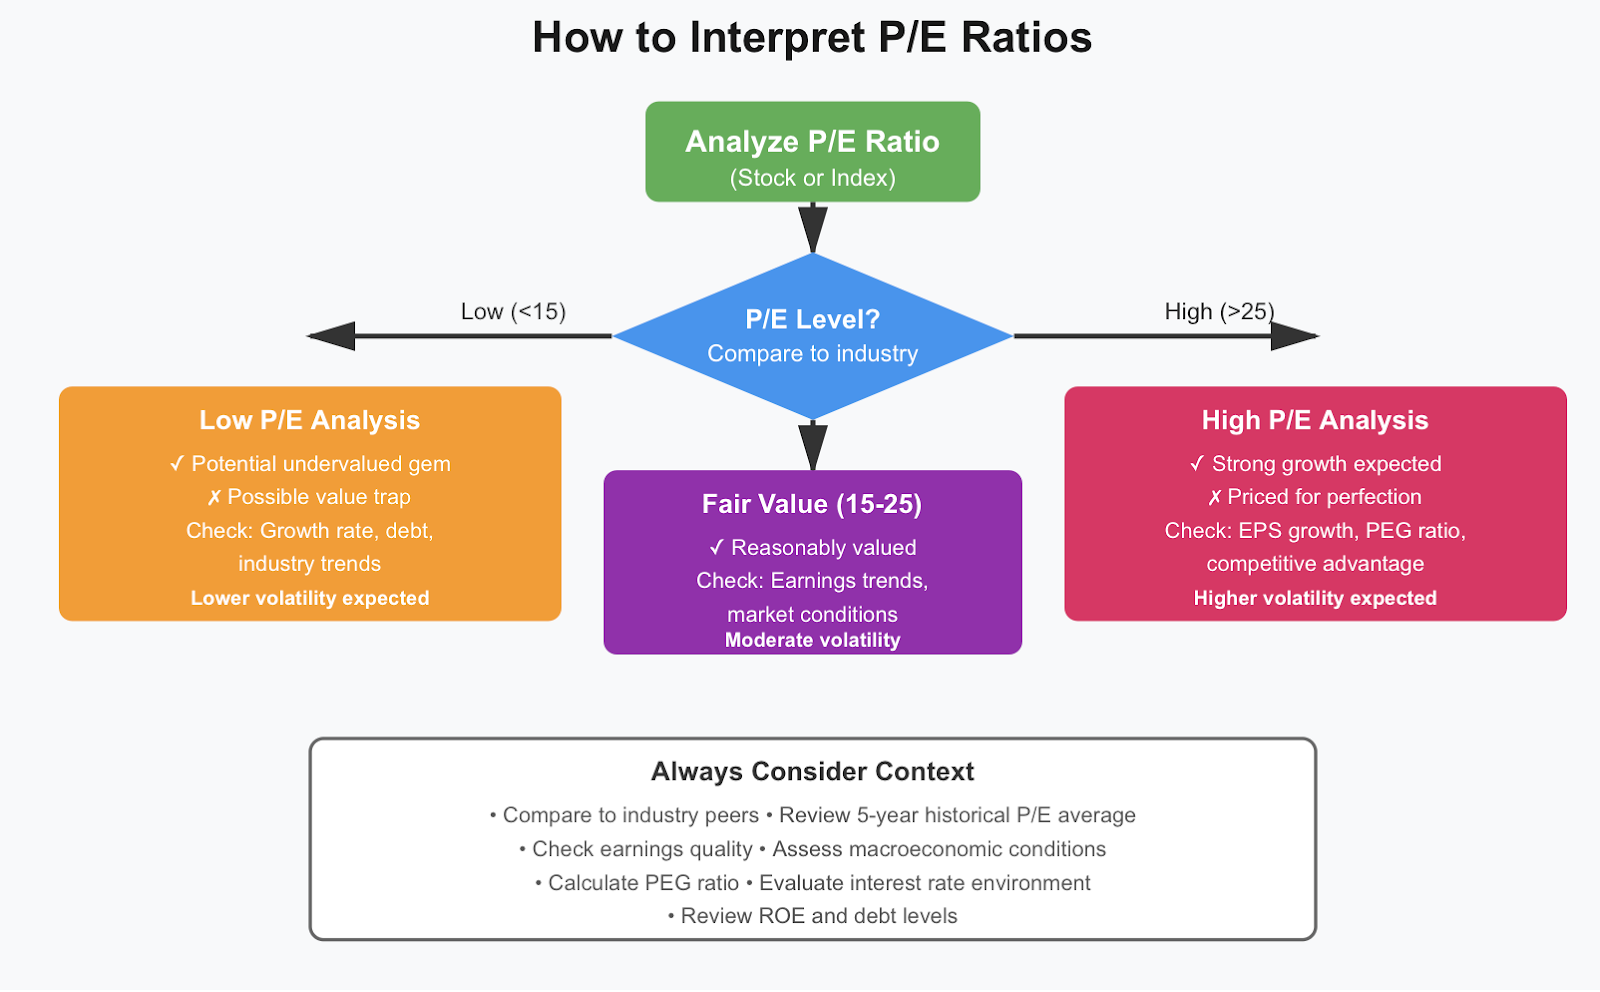
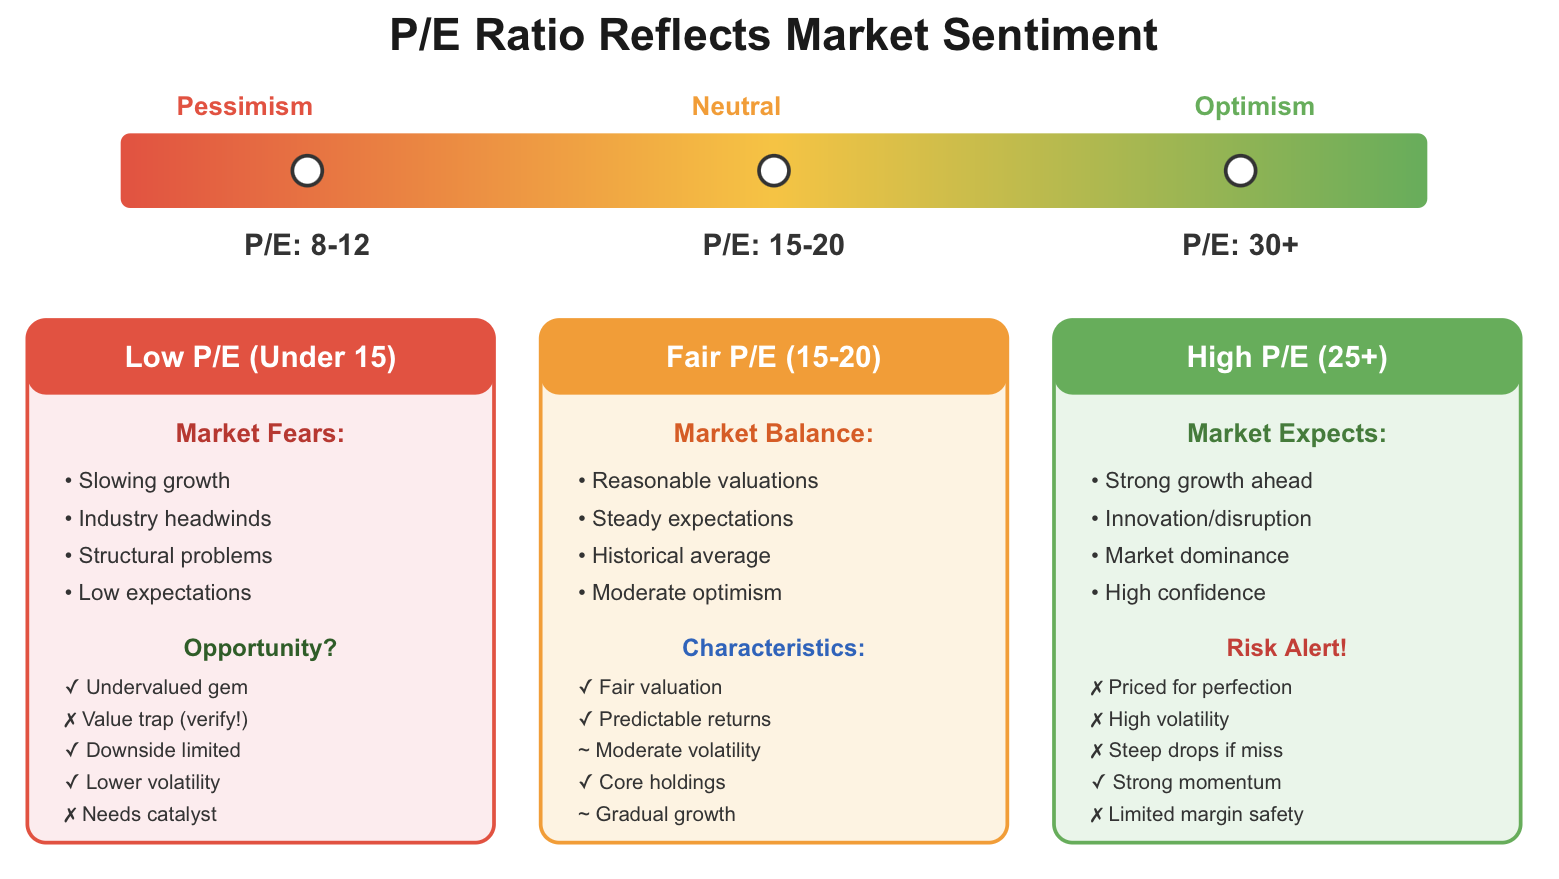
If the stock P/E ratio is high, (for example above 25), this means that investors are betting that the company is going to have significant future growth and so this higher multiple to valuation is justified. If they are not correct, there is some risk to the stock and it would most likely come down. to illustrate, not all future earnings will necessarily justify pay a higher price today. An example is a $100 price today would be justified when the company announces future earnings many times higher than expected; however if they are not many times higher, the P/E will be useless.
A low P/E (often below 15) might suggest that the stock is undervalued and a hidden gem. But it could also mean there's trouble - slowing growth, headwinds in the sector or some other structural problem. Remember, a bargain price isn't always a bargain.
The particular industry is hugely important. Tech companies usually have a 25-35 P/E because they work in growth industries. Amazon had a ridiculously high P/E for ages (or even a P/E of 0 when it wasn't profitable) because the expectations from investors were focused on the long-term growth. When talking about a manufacturing business with a P/E of 30, the crowd would be skeptical. Ford or Boeing usually hover around a 12-18 P/E because their industries are more mature and account for slower growth.
Banks are another interesting kettle of fish. As an example, JP Morgan or Citigroup might have P/E ratios between 10-12. Not necessarily because they are failing as businesses, banks are also very regulated, limited growth potential, and get to profits that are predictable. Better not to get excited about the business in the middle of the maturity cycle, therefore a bank will bring a lower P/E.
Here's a comparison to illustrate:
The technology company trades at a premium because investors believe it will double earnings over the next 5 years. The auto manufacturer is fairly valued at a P/E ratio signifying steady, unexciting growth. The bank's low P/E ratio indicates regulatory headwinds and major skepticism in the equity market.
One important point to mention: P/E ratios may use different calculations for the earnings figure ("trailing P/E" uses last year's actual earnings, "forward P/E" uses predicted or forecasted earnings for future time periods). Forward P/E ratios can be misleading when analysts are overly optimistic about future earnings. However, using forward P/E ratios makes most sense when considering the valuation of growth companies, where past performance may not reflect the company's potential future growth.
The bottom line? A P/E ratio is a starting point for your valuation analysis and is not the final answer. You still need to evaluate further: What is the company's growth trajectory? How does it stack up against competitors? What is happening with the economy and market conditions more broadly? A P/E ratio shows you what investors are paying, but you must determine if that price is justified.
Why P/E Matters for Stock and Index Traders
Grasping the significance of P/E will change your trading stance. This ratio isn’t just located in annual reports, it actively representation of stock prices, market wielding volatility, and investor behavior in ways that influences your portfolio as much as possible.
In the first place, high P/E stocks are less durable when the market is down. A company that is trading at 35 times earnings, its price is priced for perfection. That being said, any disappointment (missed earnings, slow growth, regulatory issues) can result in a steep death spiral. No one can blame investors that paid these premium prices. Premium prices and premium results are simply all they have come to expect. When the actual result doesn’t fit that criteria, investors won't stick around. You only have to look at many technologies stocks in 2022, for instance. In a time where interest rose and growth slowed, every stock with a price earning ratio greater than 40 got stretched thin to the extent of losing 50-70 percent in value.
This can then be compared to low P/E stocks. If a company is trading at 12 times earnings, public expectations are already very nominal. There is more upside than downside as the price point represents the cheapest form of optimism. These stocks sustain, if not gain, ground further and further down during another market stress moment.
The reasoning behind index evaluation is similar. When people mention that the S&P 500 is "expensive," they are likely referring to its P/E ratio, which has historically averaged around 15-16 times earnings; if it goes to 25 or higher, that is "expensive." Every stock within the index contributes through its market capitalization in estimating an average price-to-equity ratio. Stocks in the technology sector, such as Apple, Microsoft, and Nvidia, have considerable market capitalizations and influence index valuations. If tech stock P/E ratios are significantly higher than average, as stocks account for their weight collectively, they lift the index evaluation as well.
For CFD traders, if you're looking at P/E for similar stocks, it can also be a gauge of risk (volatility) when trading CFDs. A CFD on a technology stock, with a high P/E ratio, will likely have higher volatility than that of a utility with a low P/E ratio. Also, if you are trading with a short time horizon, significant price moves can happen if P/E is viewed unfavorably show sudden equity compression (despise the term, it means that the stock suddenly loses a lot of P/E ratio).
During the 2022 market downturns, for example, the NASDAQ Composite (overweight in high-P/E tech stocks) fell more than 30% from its highs. Stocks the trade at P/E ratios higher than 50 were smashed down, with Meta (Facebook) falling from nearly $380 to below $90 and Tesla from $400 to $100. Conversely, energy stocks that traded at lower P/E ratios, went up in value because they were undervalued and benefited from higher oil prices.
In a beginner example, think about two baskets of stocks. Basket A has high-P/E growth stocks with (P/E ratios above 30), and Basket B has value stocks with low-P/E ratios (P/E ratios approximately around 12). When the Federal Reserve announces an increase in interest rates, Basket A typically performs worse than Basket B. Why? In times of higher interest rates, the future value of the earnings will be worth less dollars in today's dollars. Since growth stocks have higher P/E ratios, their future earnings are worth higher in net-present-value, which means that their P/E ratios deflate in value, as the investor is looking for cheaper valuation to buy.
The link between price-to earnings and volatility is not only theoretic. Many studies and data indicate that high-P/E growth stocks will bounce around more than value firms, whenever, there is new information about earnings, or macroeconomic information (such as GDP) or changing in market sentiment. For traders, this means:
-
Day traders and swing traders may gravitate toward high-P/E stocks for a potential larger return, but must also use that stock with tight stop-losses.
-
Position traders and investors may lean toward more reasonable P/E’s for a steadier return and a bit less angst.
-
Index traders will use the sector P/E to see how to trade for rotation (money rotating out of an expensive sector into a cheaper sector.).
There is one more very subtle effect. P/E ratios can also affect an institutional buy-in. Many funds have mandates that prevent them from holding stocks that are above certain P/E thresholds. When a P/E ratio rises too high , the fund must sell the position; this will add pressure as well. When a stock's P/E ratio decreases to a value range, it creates more institutional buying in the stock.
This is where you will see the most value - follow P/E trends, snapshots don’t matter. A stock at P/E of 25 is not expensive or cheap, but if this stock was at 40 six months ago, then it is becoming more reasonable. If it was at 15 last year it might be getting frothy. Assuming you know how to use valuation trends, you will know when prices are normalizing or getting frothy.
Index traders can use the major indices' P/E ratio as an indicator to get a very general macro perspective. When the S&P 500's P/E is in the 25-30 range, based on historical observations over the next 5-10 year period, returns are typically considered lower than historical expectations. Conversely, when the S&P 500's P/E ratio is below 15, higher subsequent returns can typically be experienced in the years that follow. This does absolutely nothing to help if you are day trading for the next day or the next week, but it serves to steer your relative position in a broader macro strategy.
The practical lesson is: P/E ratios really matter because - these are sentiment indicators and based on extreme valuations, they tell you when you are too far to the optimistic side and when you are too far to the pessimistic side. This is valuable intelligence for any trader.
Industry Differences & Market Context: Reasonable P/E Ranges
Not all P/E ratios are equal. A P/E of 30 may be perfectly fine in one industry but a warning sign in another. Understanding these differences saves you from doing lazy comparisons and to miss the real story.
Technology companies often trade with much higher P/E ratios, more than a 25-40 P/E ratio or higher. Why? Because of the idea of growth. A software company can grow quickly without significantly added costs. Apple, Microsoft, and Nvidia have high P/E ratios because investors believe they will continue to grow revenues and profits. So when looking at a tech stock, compare it to other tech stocks and not the market. A tech stock of 22 P/E might be cheap in comparison.
Manufacturers and industry type stocks are fall somewhere in between. Stocks like Ford, Boeing, and Caterpillar trade around a P/E somewhere around 12-18. These companies are constrained by real physical constraints. Growth requires building factories, supply chain complexity, and cyclical demand. Because of these constraints, higher P/E ratios often add the idea they are currently retrenching rather than looking for growth. For example, if Boeing P/E ratio jumps to 30 P/E with no reports of revenue growth, that is due to earnings that crashed, not because there is revenue growth expectations.
Most companies in the banking and financial services sector have lower P/E ratios (10-14). Usually, banks are tightly regulated, thus they maintain low-risk taking and growth opportunities. Most banks generate steady, but mediocre returns. Therefore, a 15 P/E doesn't mean the bank is undervalued that is the normal range for banks. JP Morgan, Bank of America, and Citigroup all trade in that range most of the time.
Here's a practical comparison:Changes in macro economic conditions tend to change everything. Lower interest rates make investors more tolerant of higher P/E ratios across the board. When borrowing is cheap and bonds yield almost nothing, stocks look compelling, even at elevated valuations. We saw this from 2010-2021. The average P/E ratio on the S&P 500 rose from 15 to over 30 at its peak.
Then interest rates start to rise, and the environment reverses itself. Higher rates make bonds more competitive with stocks, but importantly it makes future earnings less valuable today (pursuant to the discounting effect). Suddenly, a P/E ratio of 30 may look ridiculous when you can earn a safe 5% on bonds. The stock prices for high-P/E stocks get repriced lower.
Economic cycles matter as well. In recessions, earnings tend to be less stable than stock prices and tend to collapse faster. This results in surprising spikes in P/E ratios. A stock may go from a P/E of 15 to 40 not because the price doubled but because the earnings quartered. Clever traders look through this and understand the earnings will recover, i.e. the elevated P/E ratio is transitory.
On the other hand, earnings increase during periods of economic expansion. As earnings grow faster than prices, stocks will rise, which can push P/E ratios lower (downwards). This is actually bullish, as it indicates management is delivering better outcomes than what the market was expecting!
Currency and inflation also come into play. Not only is nominal earnings in high inflation environments increased, but the real value is diminished. Companies will indicate they have earnings growth of 20%, however with inflation at 15% the real earnings growth is only 5%. Investors will reduce P/E expectations based on these real growth rates. Ultimately you will see an overall reduction in P/E ratios, as the quality of the earnings is of concern!
Another aspect is geographic quality. Emerging market stocks will typically trade at lower P/E ratios than the developed markets. This is partly due to higher expected risk, higher discount rates, but also due to different growth trajectories. Chinese stocks in the technology space trade at P/E ratios that are sometimes 30-40% lower than comparable companies in the US, with comparable growth rate.
The key point here is that P/E cannot be viewed as "the less, the better" or "the more, the better" and context matters. As an example, if I have a utility company with a P/E of 30, it is probably overpriced. Conversely, if I have a biotech company that has a P/E of 30 and is developing cutting-edge drugs, then it may be undervalued. You must learn to compare and look at central tendencies between similar types of companies and adjust for economic conditions.
As you're evaluating a stock, consider asking:
-
At the present time, what is the average P/E for the industry?
-
How does this company's P/E really compare to its direct competitors?
-
Where are we in the economic cycle?
-
What are interest rates and inflation doing?
By answering these questions, you will know if that P/E ratio is sign of opportunity or danger.
How to Use P/E Ratio in Trading Strategies
Understanding what P/E means is one thing. Using it correctly, in your trading, is another. The ratio becomes useful when you interpret it with other ratios and develop it to fit your trading style.
Get back to basics. P/E ratio should not be the only metric used in your analysis. You can pair the P/E with:
-
ROE (Return on equity) - which explains how well the company can generate profit versus the shareholder's equity in the company. For instance, if a stock has a P/E of 25 and a ROE of 30%, this company is a better trade option compared to a company with a P/E of 15 and 5% ROE.
-
Earnings per share (EPS) growth rate - tells whether they are accelerating in earnings or decelerating. If a stock has a P/E of 30 and annual EPS growth of -40%, it is a more attractive trade than a P/E of 12 and year over year flat earnings.
-
Debt-to-equity ratio relative to P/E - the greater debt of a company leads the company to take more risk into account therefore making a lower P/E company with significant debt a potential value trap.
-
Current ratio - the current ratio in relation to P/E, for instance, if a company has a current ratio of 1: or 1 to 1, that would represent a company with current assets equal to current liabilities, that can have significant impact on P/E ratio analysis.
For long-term investments, P/E serves as a screening mechanism. You may want to filter for stocks with P/E ratios below their five year average indicating that they might be undervalued, or you may want to look for companies traded at P/E ratios 20-30% below their industry average. Neither example on their own guarantees a successful investment, but they do provide some stocks worth further analysis.
Professional Example: You are evaluating two tech stocks. Stock A has a P/E of 28, EPS growth of 35%, and ROE of 28%. Stock B has a P/E of 18, EPS growth of 8%, and ROE of 12%. At face value, Stock B appears cheaper, but when you consider the PEG (P/E divided by growth rate), Stock A does come out ahead: 0.8 vs 2.25. Therefore, Stock A is a better value stock even with a higher P/E ratio.
For the short-term trader or CFD trader, P/E can provide insight into momentum and risk. High P/E stocks are more volatile, which can offer larger moves, but you need to consider your risk management strategy as well. If you are doing some swing trading, look for expansion (increasing) and contraction (decreasing) of P/E ratios. In the case of expansion, for example, if the earnings continue to exceed estimates, the expansion can't go on forever but it typically means increased upside. However for contraction, if the earnings come in lower than expected, then the contraction usually brings with it more selling.
Investors can also utilize P/E to trade sector rotation. When defensive sectors (e.g., utilities, consumer staples) become associated with higher-than-usual P/E ratios while cyclical sectors (e.g., technology, industrials) exhibit contraction in valuations, we may expect an economic recovery is beginning to take place. As economic optimism returns, money flows from expensive defensive stocks to more reasonable growth stocks.
Example for Beginners: Think of P/E as grocery shopping. If the price of milk rises from $4 to $6, you will ask the reason. Either there is a shortage (earnings contracted) or the price reflects a premium for organic milk (growth story). Either way, you are not buying a gallon of milk without asking why the price increased. This is the same for investing in stocks. A tech company listed at a P/E ratio of 50 could be overvalued, or it could be the next Amazon. Your job is to figure out the why.
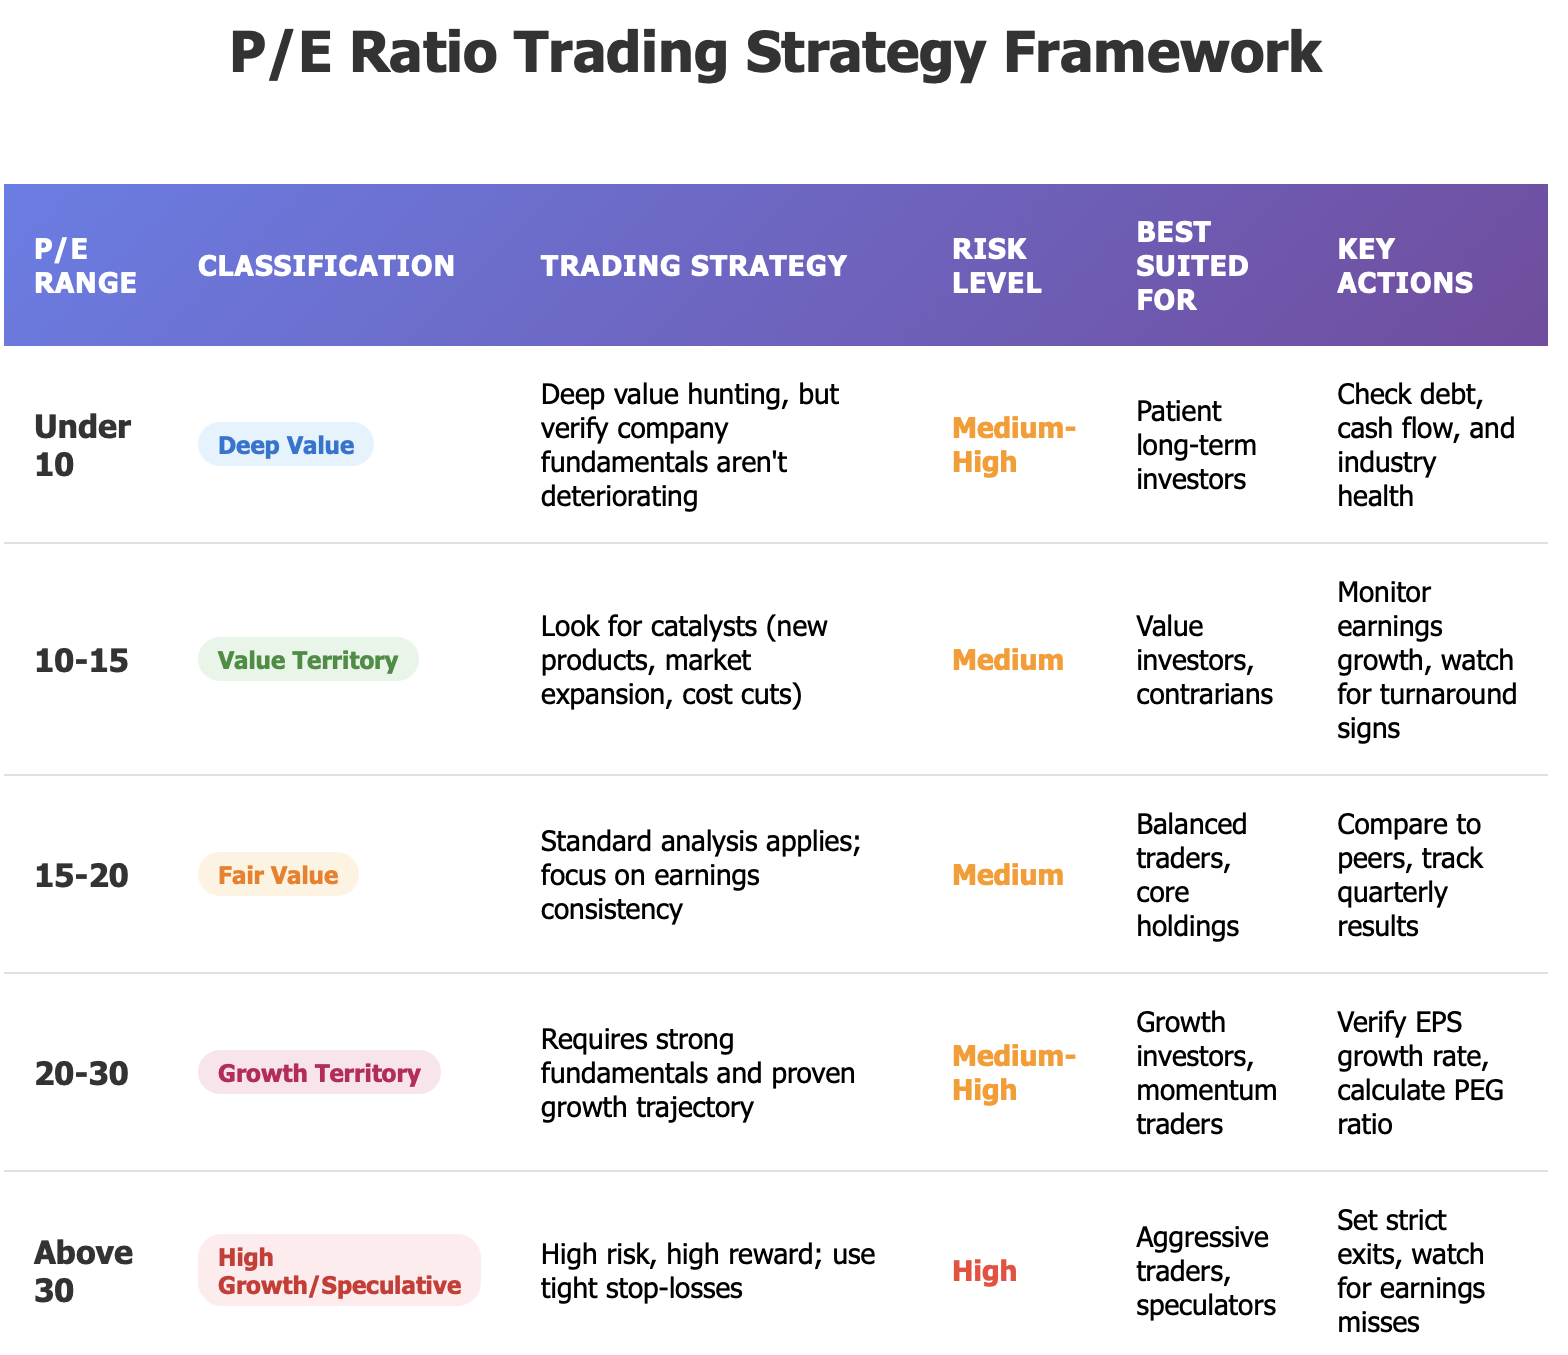
Here's a practical framework:Integrate P/E with analysis methods. An attractive P/E is not an immediate buy signal. Look for confirmation through: resistance breakout, moving averages golden cross, or a bounce off strong support. Value traps (cheap stocks that keep going down) happen all the time. Price action shows whether your assessment of valuation was in line with other investors.
For ETF/index traders, the P/E of a major index is a chance to determine macro positioning. Generally, if the S&P 500 is in the 22-25 P/E level, it's a good time to (if) start thinking defensive: shorter duration trades, tighter stops and may be short bonds, and will reason.
If P/E is below 15 then it's generally time to get aggressive.
Monitor the earnings season. Companies provide their quarterly results during earnings season and they issue EPS. In addition, you may see a company that has a P/E of 25 based on last year's earnings, but this year's earnings can be 18 because of the next (forward) earnings will capture this. In this regards EPS and forward P/E can be much more useful than just looking at P/E. That said analysts estimates can be wrong, so you always want to see if projections seem reasonable.
An advanced approach: contrarian P/E plays. When a particular column becomes out of owners' favor and P/E ratios compress significantly, traders with discipline may have an opening. Energy stocks in 2020 traded at single-digit P/E ratios as oil prices were crashing. Those who bought and held for the following years of 2021-2022 had huge returns on their investment. The difficult part is figuring out if it is merely temporary pessimism or if it is actually a structural decline in the business model.
The most important single principle: P/E is never standalone. It is one data point in the whole analysis. Utilize P/E to consider areas of opportunity, but then it is time to do more digging into the situation. Read earnings calls, understand the business model in context; assess management and considerations for a competitive advantage. P/E starts the dialogue, but it does not end it.
Case Studies: How P/E Ratio Impacts Real Investment Performance
Theoretical frameworks are valuable, yet tangible instances of investment theory captivate the learning experience. With this in mind, let's review a practical application of how P/E ratios can manifest within real market conditions and events.
Case 1: P/E Expansion in Apple Inc. (2019 - 2021)
In early 2019, Apple Inc.'s stock was trading at a P/E of around 12 - 13, which was extraordinarily low when measured against its peers in the technology sector. There was some pressure on the stock due to investors' concerns over flattening iPhone sales, market saturation of the smartphone industry, and Apple's iPhone-focused business model. Thereafter, and leading into 2021, Apple's P/E expanded from 12 - 13 to around 35. The stock went from around $200.00 to over $700.00.
What transpired within the 2-year period? As at that time, Apple's expanding P/E was a reflection of what investors were saying about the company's prospects. More specifically, Apple began growing its services (Apple TV+, music services, and cloud storage like iCloud) and announcing new product launches (dominance in AirPods and Apple Watch), among other criteria.
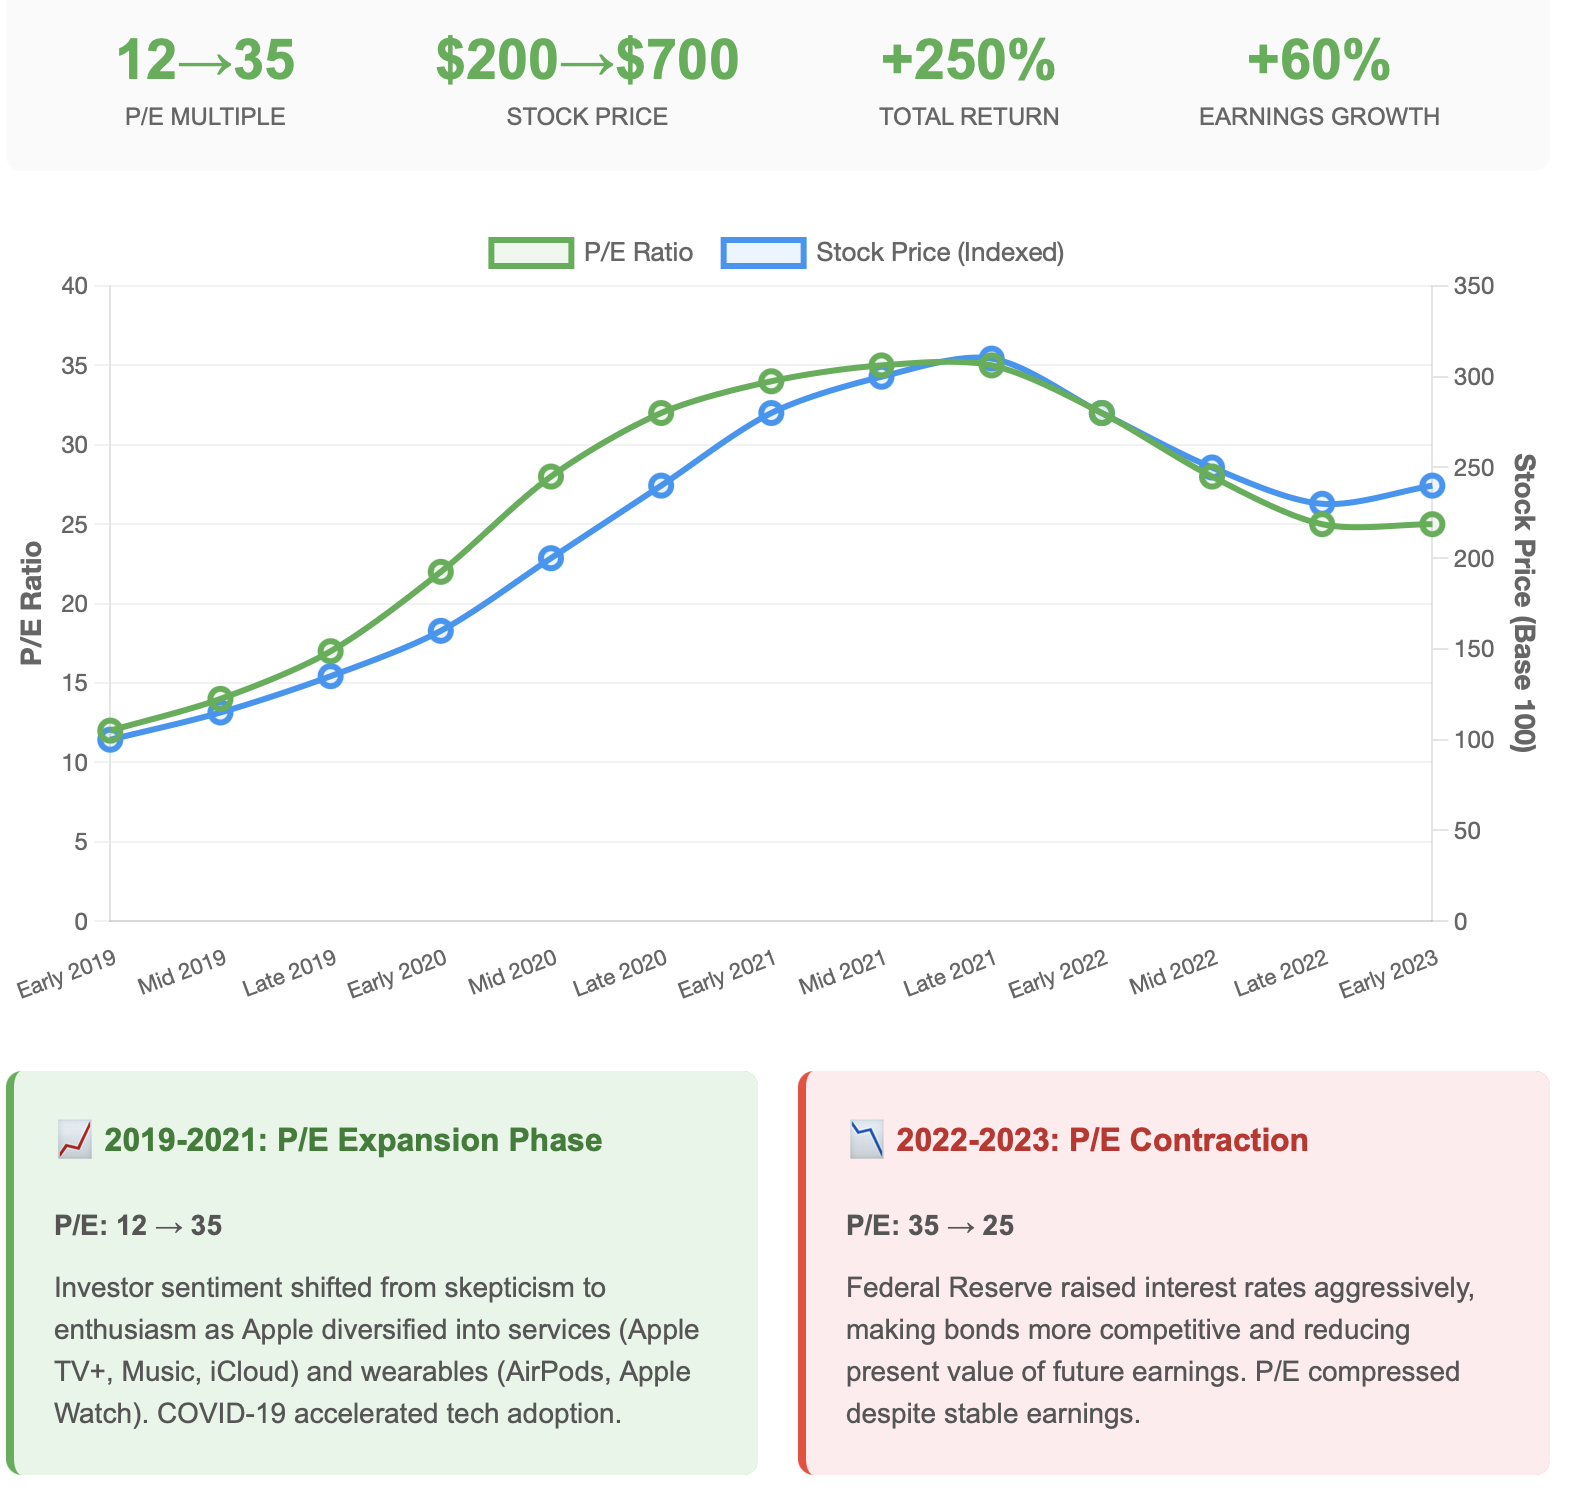
Additionally, demand for technology spiked due to the COVID-19 pandemic, which resulted in operating earnings growing around 60% over the two-year period, however the stock had appreciated 200%+ based on P/E expansion. The learning here is that P/E expansion can contribute to return on investment, faster than operating earnings growth. When the outlook on the stock changes from skepticism about the company's standing to enthusiasm, P/E multiples begin to expand. The inverse also occurs. In 2022-2023 Apple's P/E contracted from 35 down 25 (i.e. to reflect a higher rate environment) while earning remained intact.
Case 2: Banking Industry Amid Rising Interest Rates (2022-2023)
In January 2022, traditional banks (JP Morgan and Bank of America in particular) had price-to-earnings ratios of approximately 9-11 times (which shows concerns of an industry that has been suspicious for some time). Then, the Federal Reserve began raising interest rates quickly. Higher interest rates should improve banks’ net interest margins (fewer loans at lower rates means receiving more interest income). Earning improved by 20 to 30 percent for the larger banks in 2022, but the price-to-earnings ratios stayed in the 9-12 times range. Stock prices rose with earnings, so the earnings drove stock prices higher. Why didn’t the price-earnings ratios expand? Investors worried about loan defaults as the economy was tightening. After years of poor performance, the industry had to convince investors of its worth.
Lesson: Growth in earnings will not automatically increase price-to-earnings ratios. Structural uncertainties and risk can limit or compress multiples. Even with low price-to-earning ratios, and if held long enough, can provide reasonable good returns off only earnings growth with no increased multiple.
Case 3: Tech Bubble Signals (2020-2021)
Following 2020 and throughout 2021 many unprofitable tech companies showed up on both SPACs and IPOs. These companies often had earnings per share greater than infinity, or many projected 100x earnings per share. Additionally, some companies (Snowflake) came public with valuations greater than 100 revenue (not earnings); similar to a tech bubble.
In late 2021, the average price-to-earnings (P/E) ratios for unprofitable technology companies reached levels that had not been witnessed since the dot com bubble. Market participants who saw the warning signs proceeded to take action. Once the Fed flipped to a more hawkish stance in 2022, things turned ugly fast. Companies like Peloton were down over 90%. DocuSign was down over 75%. Even profitable growth stocks like Zoom saw share prices fall about 70% as the multiple for P/E ratios fell from over 50 times earnings to under 20.
Key lesson: Extreme P/E ratios, particularly for unprofitable firms, indicate danger is likely ahead. At some juncture mean reversion happens to valuations that's meaningfully were detached from fundamentals. It's not really about pinpointing the timing of the top, but rather identifying when the risk-reward structure to heavily negative.
Case 4: Value Play in the Energy Sector (2020-2021)
In 2020, energy stocks were pricing a severely depressed single-digit P/E as a result of the total collapse of oil prices earlier than the pandemic. ExxonMobil was trading at a P/E of 8. Chevron was trading at a P/E of 10. The entire sector was hated, with the common narrative being that the sector was in a structurally declining phase as a result of renewed emphasis on the transition to renewable energy.
Contrarian prices saw a major buying opportunity. By 2021, demand for oil had materially improved, and the world was on to returning to the normal average day in the future of 2019. By the time 2022 rolled around to return above $100 a barrel, those companies were reporting the highest earnings in their storied histories. While P/E ratios only expanded slightly as they had started to return to normal at about the range of 10-12, in many cases, price had been doubled or tripled in value as a result of meaningfully increased earnings.
Key takeaway: Low P/E in sectors despised by the public can be a signal for opportunity provided you think that the fundamentals will improve over time. You do not necessarily need P/E expansion to make money when stock prices have troughed, simply earnings growth will deliver you the return if you purchase at trough valuations.
These examples show the duality of the investment returns when P/E is in play: earnings growth and P/E expansion / contraction. Your total return reflects both. The best investments will achieve both (Apple 2019-2021). Good investments can achieve either (the banks with earnings growth). Bad investments can have both reverse simultaneously (tech stocks 2022).
When you think about your investment remember to ask yourself, Am I betting on earnings growth, P/E expansion, or both? If one doesn't occur, what is my margin of safety? The answer to this question can guide your position sizing or risk management.
FAQ: Common Questions About P/E Ratio
What is a reasonable price to earnings ratio?
There is no one size fits all answer. It depends on the industry, growth rate, and economic environment. A P/E of 15-20 may be government as "average" for a mature company. Tech and growth stocks could reasonably trade at a P/E of 25-35. Banks and utilities range from 10-15. Comparing a company to is respective industry, and their own historical average, is important.
Is having a high P/E bad?
Not necessarily. You could justify a high P/E if earnings are growing quickly. Amazon traded with a high P/E for years while they built their empire. What you need to look for to justify a high P/E is growth. Having a high P/E ratio is not bad until growth in earnings stops and we still have a high P/E. That is when crashes happen.
How does price to earnings relate to growth potential?
The PEG ratio (P/E divided by earnings growth rate) serves as a guide. A P/E of 30 with 30% earnings growth means the PEG ratio is 1.0, which is fair value. A P/E of 15 with earnings growth of 5% means the PEG ratio is 3.0, resulting in overvaluation even with a low P/E ratio. A fast growing company's earnings can justify a higher P/E ratio.
What is the difference between stock P/E and index P/E?
An index P/E is the weighted mean of all the component stocks, and tells you whether the broader market is cheap or expensive. The historical average P/E for the S&P 500 is around 15-16. When it goes above 25, that is historically expensive. Below 13-14, that might be an opportunity. When comparing individual stock P/Es, it is more meaningful to compare P/Es of stocks in the same industry, rather than the overall market index P/E.
How can CFD traders use P/E for risk management?
Higher P/E stocks are usually more volatile, which matters when you are using leverage. If you are trading tech stocks that have P/Es above 40, expect huge swings and use tighter stops. Lower P/E stocks might lead to less volatile trades and lower risk for gap moves. P/E is also useful to understand what you are actually trading: meaning are you betting on growth (high P/E) or value (low P/E)?
Can the P/E ratio be negative?
While the answer is "no" generally speaking -- if a company has either zero earnings or negative earnings (which means the company's exactly breaking even or losing money) then the P/E calculation is technically doesn't work. You will sometimes see "N/A" or "negative P/E" on financial websites. These number is useless as a metric. In general you will want to look at a company's price-to-sales ratios, or other such metrics that may better apply.
Should I only invest in低 P/E stocks?
Not necessarily. A low P/E can either indicate value, or more serious problems: An unintelligent, sanguine (as in a negative trend) or declining business model. Some low to no growth stocks can remain cheap for good reason and you can lose money if you invest in a bad low past trade. You need to justify the low P/E implies you are getting a bargain.
Conclusion: Mastering P/E Ratio for Smarter Trading
The price-to-earnings (P/E) ratio is a ratio you'll want to consider more carefully rather than just glance at and move on like another metric. It encompasses market psychology, company valuation, and risk assessment all rolled into one number. And knowing what affects the price/earnings ratio of a stock—earnings growth, investor psychology, economic conditions and macroeconomic conditions, and industry characteristics—only gives you an advantage regardless of whether you're day trading, swing trading, or establishing a long-term portfolio.
Reinforcing the core tenets: A high P/E does not mean the stock is overvalued, and a low P/E does not mean you're getting it at a bargain. Context is everything. Comparing across industries and taking growth rates into account are key. Would you consider the macroeconomic backdrop? Definitely. While examining the P/E in consideration of ROE, debt levels, and cash flow is important to understanding the context of the ratio.
For traders, the P/E can help you pick your spots. If you're looking for volatility, you want to stick to the high P/E growth stocks. Conversely, if you're looking for stability, low P/E value plays may be better suited for your trading approach. If you're trading the indices, then the overall market P/E can offer some benefit helping to understand if you're simply buying into an expensive overall market after the contraction or might you get lucky and find an opportunity to buy something with good upside potential.
Above all, use P/E as the beginning (not the conclusion) of your analysis. Consider the business, the competitive landscape, and read the earnings reports. It tells you what other people are willing to pay, but you decide if they are right.
Once you're comfortable with your analysis, practice before risking real money. Reflect on the historical P/Es of each stock you plan to trade. Compare companies in similar sectors. Record how P/E ratios change before and after earnings reports and economic news.
Feeling confident in using P/E ratios? Initiate your experience by paper trading your strategy on Tradewill's demo platform. Test strategies, develop your analysis, and establish some level of confidence before putting any of your own capital at risk. Practice is what will separate the knowledge base of knowing about P/E ratios and profiting from P/E ratios.
Disclaimer: The content of the blog does not represent any position of Trade W, does not serve as any trading-related decision advice, and does not endorse any third-party.